Executive management of Selvaag Bolig ASA
Group CEO | ||
COO | ||
EVP communications, sustainability and corporate strategy | EVP market | CFO |
Executive management of Selvaag Bolig ASA
Description of the business
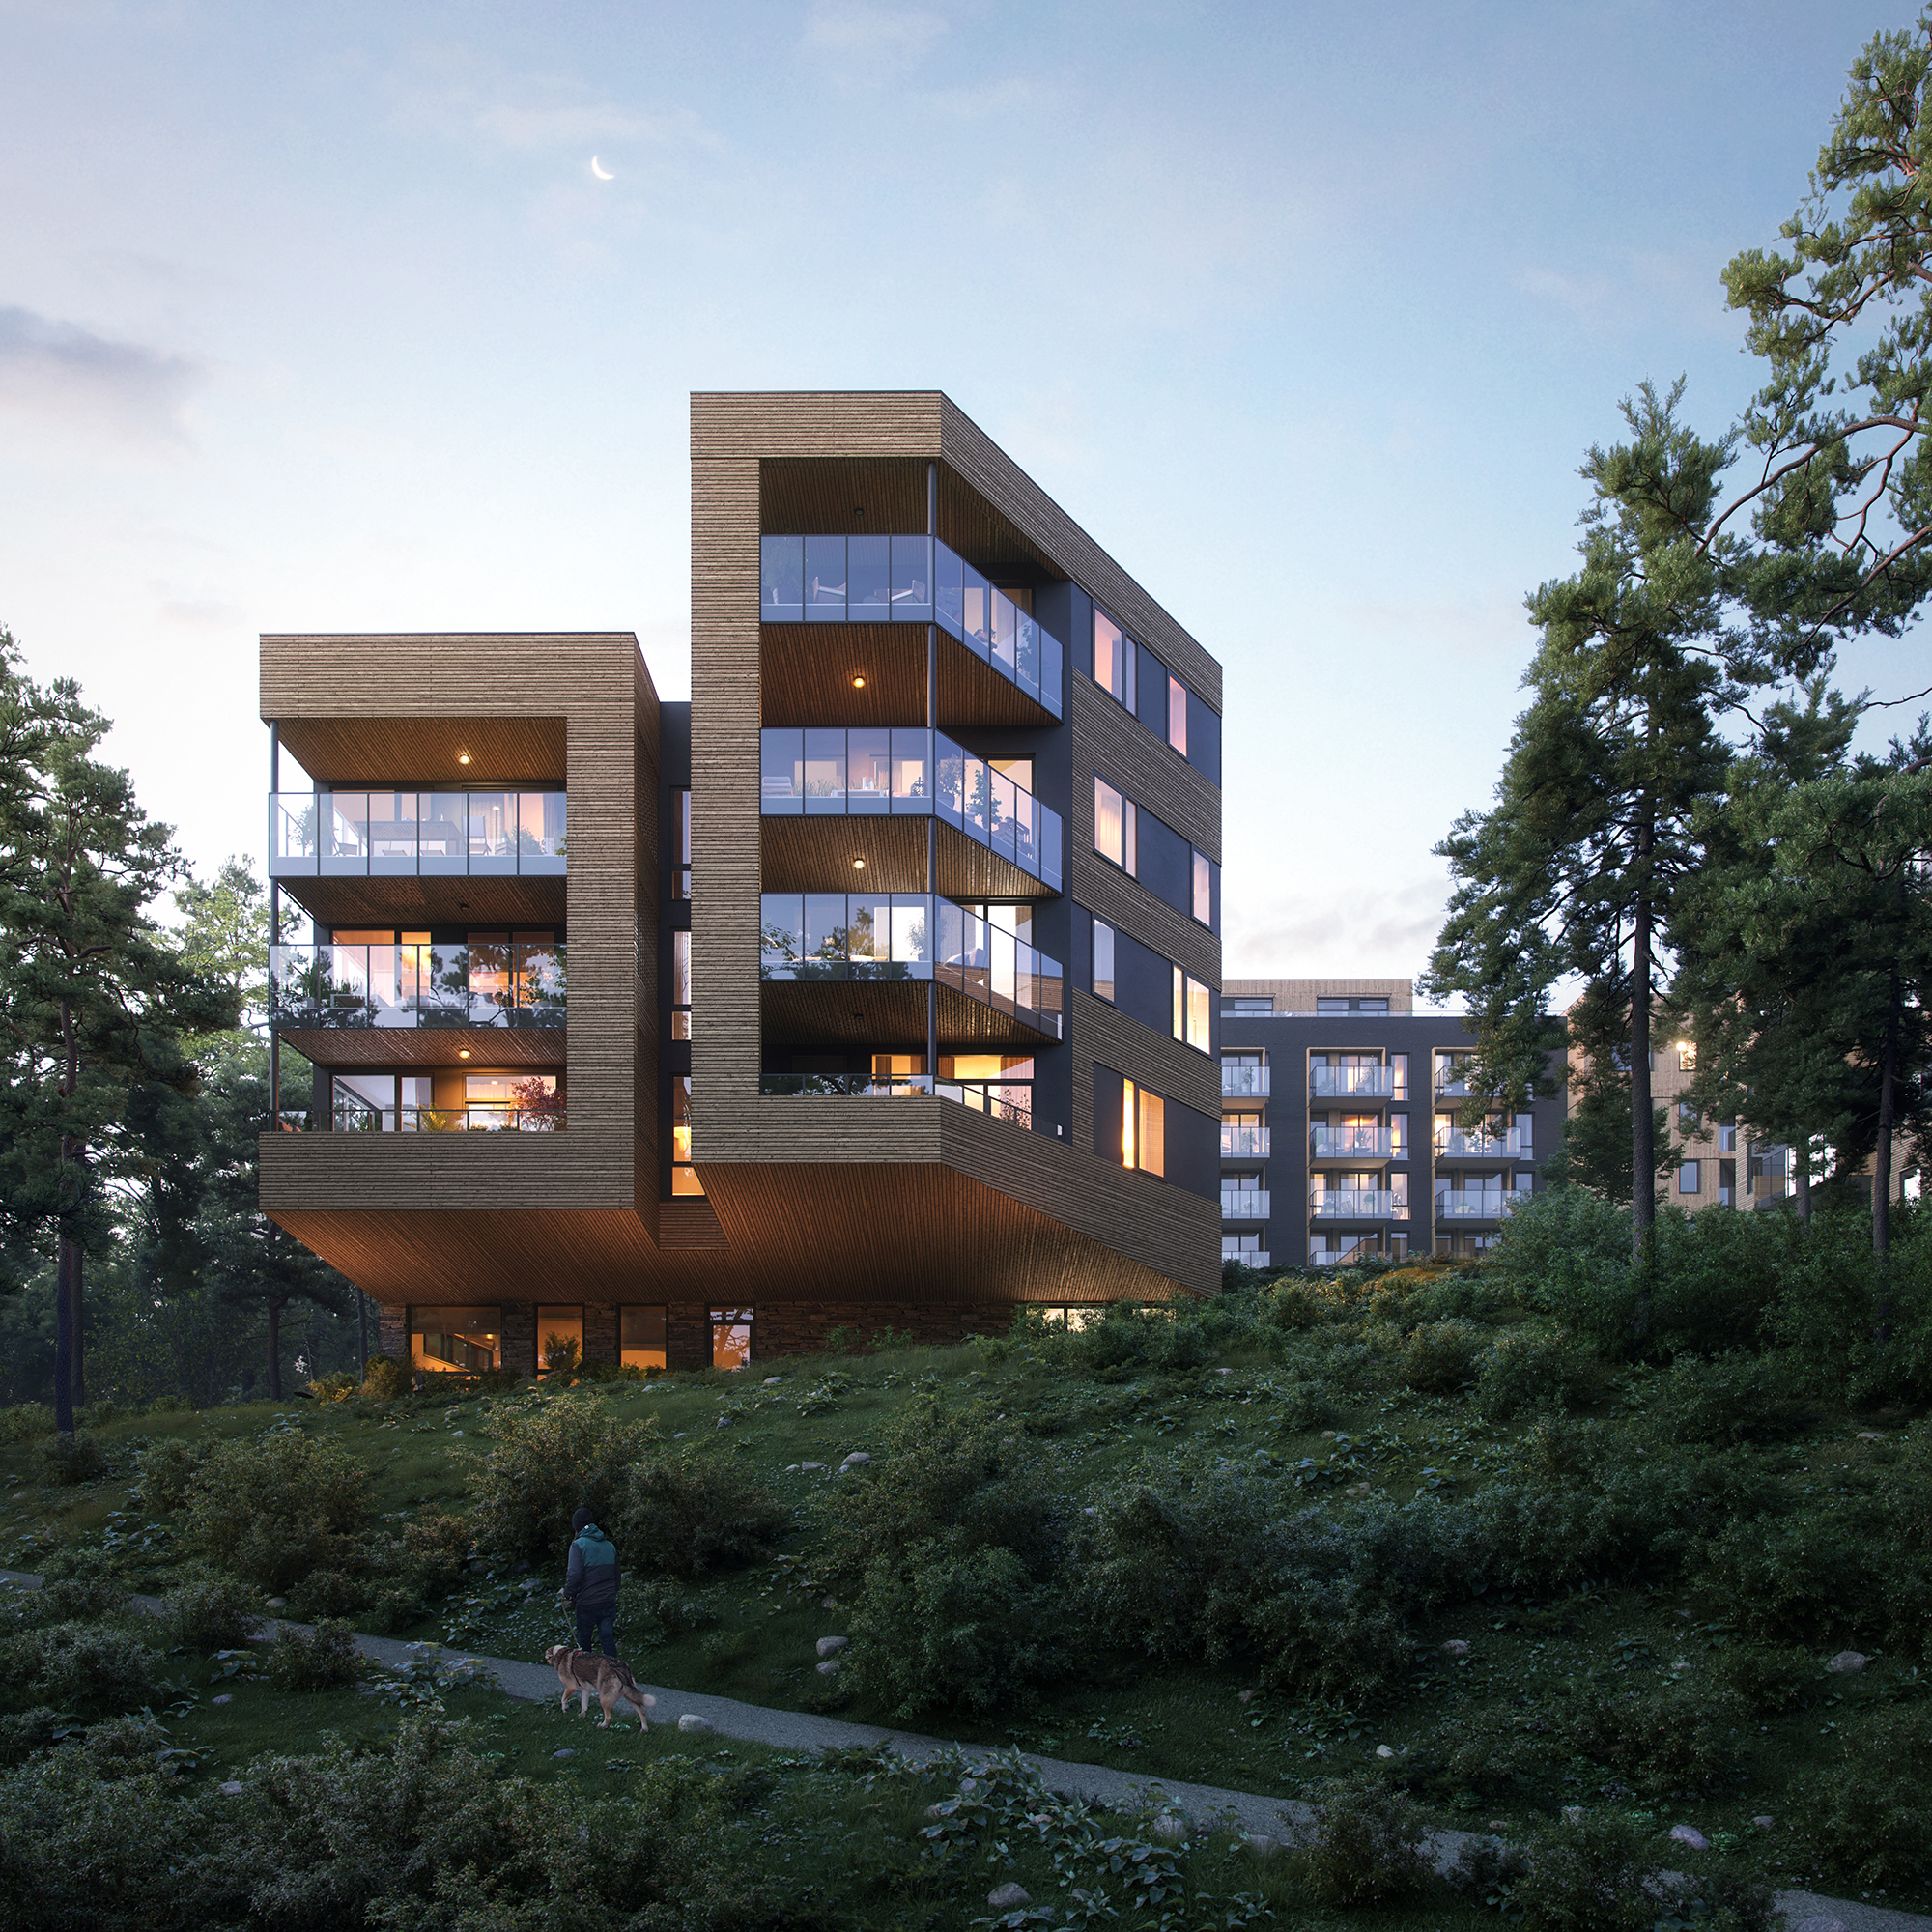
Selvaag Bolig is a housing development company which offers homes tailored for specific customer groups in the growth areas in and around Greater Oslo, Bergen, Stavanger, Trondheim and Stockholm. By offering good housing at competitive prices, the company will give as many people as possible, in all phases of their lives, the opportunity to own a home. The company does not have an in-house construction arm, and concentrates primarily on developing large housing projects with more than 150 homes – mostly in the NOK 4-6 million price category. By subjecting construction to competitive tendering, the company reduces risk and achieves better prices. Selvaag Bolig has also employed service people in the wholly owned subsidiary Selvaag Pluss service AS. They work as hosts and maintenance people at the company’s Pluss Homes – homes with shared facilities and services which Selvaag Bolig operates after delivery to the customer.
There have not been changes in the company’s areas of business or value chain in 2022.
Company structure
At Selvaag Bolig, all projects are placed in separate project companies. Most of the project companies are wholly owned by Selvaag Bolig ASA, and do not have their own employees. They are subsidiaries that are consolidated 100% in the group accounts. In addition, Selvaag Bolig ASA has joint ventures projects that are mainly owned 50/50 with other actors, and are classified as joint ventures/associated companies. The earnings from them are included in the consolidated accounts according to the equity method. For more information, see note 2.6 in the group accounts. Selvaag Bolig has also separated operations of Pluss Homes into a separate company. Selvaag Bolig has 86 employees of which 64 are employed in Selvaag Bolig ASA. The remainder are employed in Selvaag Pluss Service AS, Selvaag Eiendomsoppgjør AS and in Selvaag Bostad AB including its subsidiaries.
Housing range tailored to the market
Selvaag Bolig has house types and concepts tailored to different target groups with varying needs and preferences. The largest volume of the homes built by the company is designed for the biggest customer group – households with normal incomes, and the share of Pluss homes, i.e., homes with shared facilities and services has however increased in recent years. Thanks to the size of its projects, the various types of homes can be combined in each project. This contributes to socially sustainable neighbourhoods by offering homes that match all conditions of life and age groups. It also provides a range tailored to the market and helps to optimise the sales and income profile of each project.
Competitive tendering for all contracts
Selvaag Bolig is solely a developer without its own construction organisation, and manages the whole value chain from the purchase of land to the sale of turnkey homes. The company has an efficient approach to housing development which helps to ensure cost efficiency and reduce market risk. The key to this is the competitive tendering of all construction activities, and mainly entering into turnkey contracts. This offers several advantages:
- Focused organisation: 64 employees in the core business. A small organisation focusing on development and sales.
- Predictable and competitive construction costs: Tenders from several contractors, based on standard descriptions, always ensuring the right market price and construction at fixed prices. Costs fixed before sales start. Collaboration exclusively with contractors who have leading-edge expertise in implementing assignments.
- Lower execution risk: Using turnkey contracts reduces execution risk in the construction phase.
- Lower market risk: Construction costs are locked before sales start, eliminates the need for big staffing adjustments in the event of market fluctuations.
- Improved capacity: Scalable model and no capacity problems when several projects are to be built simultaneously.
Land purchasing and financing
In addition to subjecting construction to competitive tendering, Selvaag Bolig’s strategy for buying and developing new sites is central to value creation at the company. It has access to a substantial portfolio of land. That permits purposeful selection of new sites which fit with the existing portfolio and meet the market requirements prevailing at any given time for sustainability, location, size, price and development potential. The company continuously acquires land in line with an acquisition strategy which gives priority to large sites in its defined core areas.
Land purchasing and financing in Norway
Most of Selvaag Bolig’s available land portfolio is owned by the company’s financing partner Urban Property, who sells land back to Selvaag Bolig when construction starts on the projects. This model makes it possible for Selvaag Bolig to refine its core activities, increase its operational focus and manifest value in Selvaag Bolig’s day-to-day activity. Urban Property is a financially sound, well-capitalised and predictable collaborator, and an important long-term and strategic partner for Selvaag Bolig.
The collaboration agreement, summarised:
- Urban Property has a pre-emptive right to purchase new land in Norway which Selvaag Bolig wants to develop. If Urban Property does not avail itself of this right, Selvaag Bolig can use other financing solutions and/or collaborate with others.
- Selvaag Bolig has an option to buy back the land from Urban Property.
- The land is bought back in stages by Selvaag Bolig at the original purchase price plus an annual option premium of Nibor plus 3.75 per cent. A transaction fee of 0.5 per cent is also payable when Urban Property buys land from the landowner, and 2.0 per cent when Selvaag Bolig buys the land from Urban Property.
- The agreement contains financial covenants.
Advantages for Selvaag Bolig:
- No need for equity to buy land. Selvaag Bolig pays 50 per cent of the purchase price to Urban Property when taking over a site (at the start to construction) and 50 per cent on project completion.
- Higher return on equity.
- Ability to pay out a higher share of profit as dividend.
- Efficient and predictable financing of existing and new sites.
- Downside risk limited to 48 months of option premiums (break fee).
Selvaag Bolig also has land on its own balance sheet, as well as land plots it controls together with joint venture partners.
Land purchasing and financing in Sweden
In Sweden, Selvaag Bolig primarily makes agreements on land purchases through land allocation by local authorities. The allocation is normally in conjunction with a bidding competition with many actors where price is one of several criteria. Payment for the land typically occurs when the land is ready for construction to begin, and the zoning risk is thus eliminated.
Sales strategy
The company's sales strategy is the key to optimal progress and profitability in the projects. Segmentation of housing projects and optimisation of complex projects with a broad range of housing types, including extensive use of the company's trademark-protected Pluss concept, have yielded positive sales and a favourable progression of sales. As a general rule, Selvaag Bolig does not start construction until 60 per cent of the value of a building stage has been sold. The rest of the building stage is sold during the period up to completion. This makes it possible to price the units in the project in line with market price developments, and ensures income optimisation. Furthermore, the attention devoted to detailed planning, standardisation, site utilisation and strategic land development helps to secure sustainability, low construction costs and good project margins for the company and competitive house prices.
Quality requirements and ESG
Selvaag Bolig sets high standards for quality at all levels internally and has extensive requirements for products, operations and ESG with its suppliers. This helps to reduce the risk of errors in the projects, and ensure that all the homes have a high standard and meet the company's ESG requirements. Read more about this in the ESG in Selvaag Bolig chapter.
Goals
Selvaag Bolig aims to be one of Norway’s leading housebuilders, and contribute to inclusive local communities and facilitate a sustainable lifestyle. The company has a long-term objective of growth. which will not be pursued at the expense of profitability. The company’s strategy helps to secure its position as market leader and to strengthen its competitiveness. Selvaag Bolig has a stated goal of achieving project margins of at least 10 per cent.
Dividend policy
Selvaag Bolig’s ambition is to pay high and stable dividends to its owners. The company aims to pay dividends of minimum 60 per cent of net profit, paid in two instalments over the year. However, the size of the dividend will be weighed against the company’s liquidity forecasts and capital adequacy.
Work in progress risk
Selvaag Bolig works actively to reduce the risk of cost overruns and delays. This is minimised by turnkey contracts with solid construction companies which are well financed and have a high level of expertise as well as a documented ability to deliver. The turnkey contractor is responsible for delivering the project at the agreed time and price. In addition, the greater proportion of the project cost is assured because construction does not start before advance sales reach 60 per cent. Furthermore, a high degree of standardisation, combined with considerable detailing in the specifications to contractors, reduces the risk of delays in the construction process. Continuous learning at the contractors contributes further to efficient project execution and reduced risk of errors and delays.
External risk factors
Low interest rates, low unemployment, substantial household purchasing power and a high level of population growth in urban areas have contributed to a large demand for new housing – particularly in Greater Oslo, where Selvaag Bolig has the bulk of its business. However, in the second half of 2022, purchasing power and housing demand were negatively impacted by interest rate increases, energy prices, inflation and geopolitical tension. The pandemic and the war in Ukraine have in addition led to higher construction costs which have delayed sales and construction starts. Negative shifts in demand could also occur because of regulatory changes that impact purchasing power or construction costs. One example of this is that climate change could lead to stricter environmental requirements in project development and affect access to new land, contractors and raw materials. See the separate section about risk in the chapter about corporate governance.
Value drivers in Selvaag Bolig
Competitive products in growth areas
- Concentrates exclusively on urban growth areas with high demand for housing and market depth.
- Competitive prices providing a large customer base.
- A broad range of house types which reach more market segments and maximise income in the projects.
Large, actively managed land bank
- Land bank owned by others ties up less capital.
- Value creation through initial and further development of land as well as its optimisation.
- Flexibility to develop several thousand homes in urban growth areas.
- Active capital management
Effective and flexible cost structure
- External construction organisation gives flexibility, reduced risk and cost optimisation.
- Project-based business model increases flexibility and reduces risk.
- Large projects with more than 150 homes provide economies of scale.
- Lean and efficient organisation reduces overhead costs.
Capital-efficient business model backed by solid balance sheet
- 60 per cent advance sales as the main rule before project start reduces the need for project finance and the risk of inventory build-up.
- Healthy debt structures and financial flexibility.